28 Jun 2012
IPO

A blockbuster public-market debut
FGV listed on Bursa Malaysia in what the group describes as the world's third-largest IPO of 2012. FGV raised RM4.5 billion from the listing exercise.

Malaysia · Capital-market case study
FGV’s story is not simply about a large listing. It is about what happens after capital arrives: operating scale, integration, cycles, governance, ownership—and eventually the decision to leave the public market.
The public-market arc
This is the useful founder lesson: the listing event is only one moment. Integration, commodity cycles, governance, execution and ownership structure determine what happens next.
FGV listed on Bursa Malaysia in what the group describes as the world's third-largest IPO of 2012. FGV raised RM4.5 billion from the listing exercise.
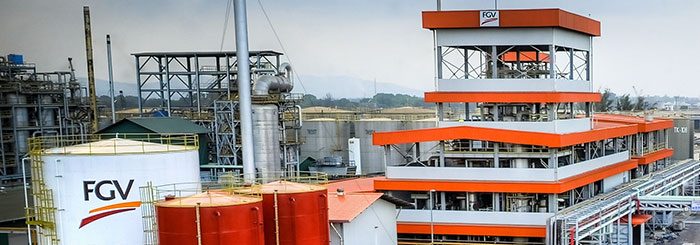
FGV acquired the remaining 51% of Felda Holdings Berhad from KPF for RM2.2 billion, deepening control across the integrated plantation value chain.

FGV reported RM25.56 billion of revenue and RM2.33 billion of operating profit, its highest operating profit since listing, helped by stronger palm-product margins and logistics performance.
FGV was officially delisted from Bursa Malaysia following its ownership realignment with FELDA, beginning a new phase focused on long-term operational and strategic alignment.
The iPivot angle
A large IPO can fund scale, but long-term value still depends on disciplined deployment and operating execution.
Integrated assets matter only when productivity, cost control and capital allocation remain strong.
Commodity businesses can enjoy powerful upcycles, but leverage and fixed costs reduce flexibility when conditions reverse.
A public listing is one ownership chapter, not necessarily the permanent destination for a business.
Source discipline
This case study is for general education and market context only. iPivot is not representing that it advised FGV, and no securities recommendation is made.
Where is your company on this journey?
Capital is only useful when strategy, governance and operating execution are ready for the next stage.